

Today I am presenting you with a US mid-cap company offering a 12.7 % FCF yield, backed by a freshly announced aggressive 10% buy-back programme. The firm is deep into a transition from a traditional model to a recurring-revenue one—and ultimately to an even better, higher-margin SaaS profile—guided to double free cash flow by 2027. It already holds roughly 36 % share in its market, enjoys a wide moat inside what is effectively a duopoly, and still trades below its weaker peers despite better margins, a clear SaaS pathway, and far stronger growth.
We have multiple catalysts in an unloved industry that, as you’ll see, offers a genuine contrarian set-up. The stock remains cheaper than lower-quality competitors, largely under-followed and overlooked because investors misunderstand the space—an attitude that looks primed to change.
This is what happened when its main competitor announced buy-backs—smaller than the one just unveiled here.
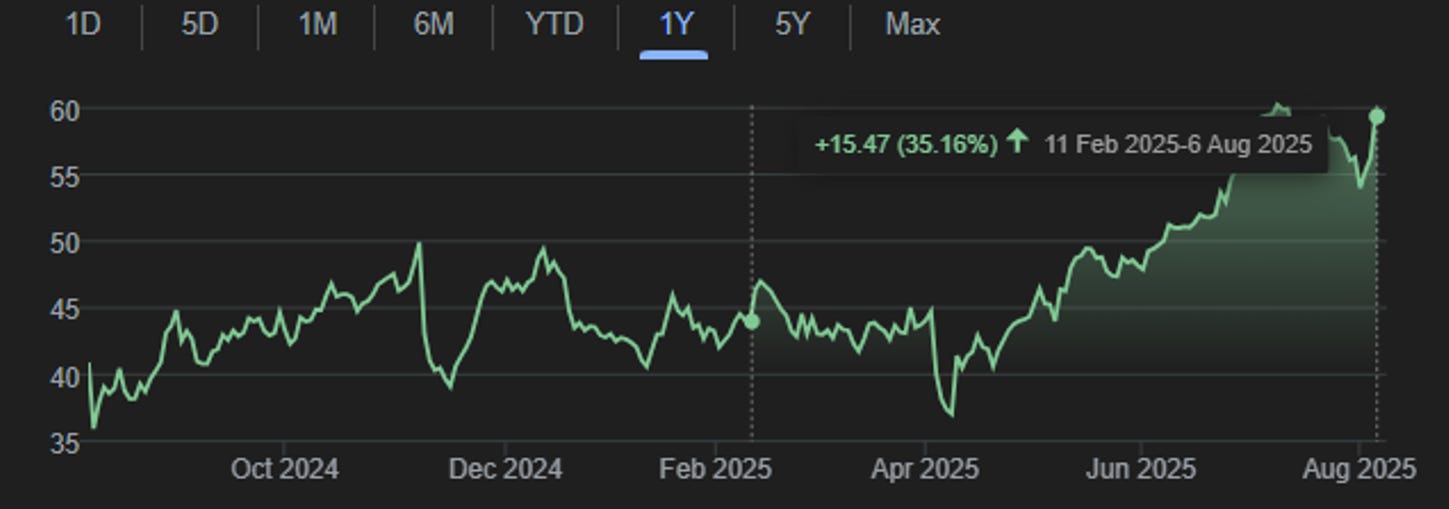
With EPS and FCF set to climb more than 20% a year—driven by steady top-line growth and rapid debt pay-downs—the new buy-back should unlock a mid-term re-rating while management proves out its superior growth profile. Add several industry tail-winds poised to lift the entire sector and the set-up becomes compelling. On our 2027 numbers, upside ranges to a 4.5× return in the best case, while even the downside sketches out a high-single- to low-double-digit IRR.
Below the paywall you’ll find:
Full breakdown of the debt, maturities, FCF increase of repayments.
Business model of the three divisions.
Three valuation frameworks—buy-back machine, status-quo, and sector re-rating—plus the downside cases that still clear a low-double-digit return hurdle
Deep explanation of why the market is getting it wrong with this company and sector.
Q2 update + short term narrative and catalysts.